Geoarbitrage for New Zealanders: Could Living Somewhere Cheaper Be Right For You?
You are reading an independently ranked global top-50 investing and finance blog. Become Wealth is independently owned, trusted to advise on over $1 billion, and one of only 49 New Zealand firms licensed to manage client portfolios directly.
Yes, for some people. Geoarbitrage means earning money tied to an expensive place while living somewhere cheaper, and keeping the difference. Some people do it for the money and many do it for the life: warmer weather, family, space, or a pace they prefer. The test is the same either way. After tax, moving costs, any change to your income and the trade-offs of daily life, is there an amount you keep? And would you still want the place if it turned out smaller than expected?
New Zealanders run the idea in several ways. The one the term usually describes is living overseas on a New Zealand or offshore income. Moving to Australia is a version in which increased pay, rather than reduced living costs, drives the result. For established homeowners in expensive locations such as Auckland or Wellington there is a domestic version. Sell the city house, set a purchase ceiling before you look at regional listings, and put the freed-up cash to work.
A key question in this regard is whether a move creates investable capital, or clears debt, while you are still earning. Choosing where to spend retirement is a different decision, weighed on healthcare, family and community more than on income and compounding.
What geoarbitrage is, and how the New Zealand rules differ
In finance, arbitrage means profiting from a price difference between two markets for the same thing. Geoarbitrage applies the idea to where you live: the same earnings (such as salary), or the same savings, buys a very different life depending on where it is spent. The term was popularised by American writers on early retirement, and their guides rest on features of the American system. Americans can move between states to reduce state income tax, or even live just south of the border in Mexico. Qualifying Americans living abroad can also exclude a capped amount of foreign earnings from federal tax, subject to residence and physical-presence tests. New Zealand's tax system works differently. Income tax is national, so a move within the country leaves your tax unchanged. A move overseas changes your tax residency, your eligibility for NZ Super, your access to KiwiSaver savings, and probably your healthcare cover. It also changes the currency you spend in, which matters if your savings and investments are held in a different one.
Living overseas on a New Zealand income
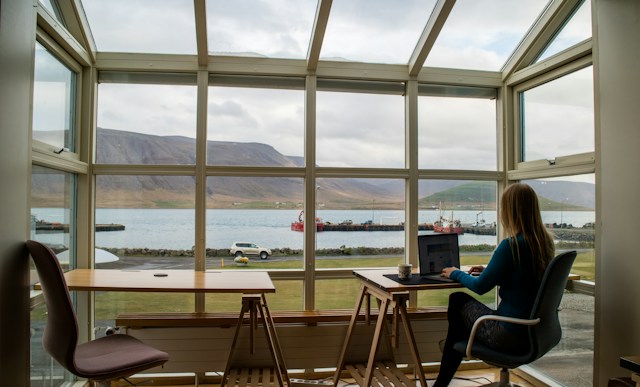
Social media feeds are full of people working from a villa in Bali. The villa is easy to market and poor evidence of what the move costs. Some of the accounts showing it are selling the course or coaching programme behind the lifestyle. Treat this sort of lifestyle content the way you would treat any finfluencer post, as advertising, until its income, tax, visa and healthcare assumptions can be checked. The appeal is understandable, and the potential appeal now reaches well beyond people who call themselves digital nomads. Many New Zealanders found in 2020 and 2021 that their job could be done from a kitchen table, and some have kept doing it that way.
Living overseas on a New Zealand income suits people whose income can travel: remote employees, contractors and consultants, owners of online businesses, and some retirees living on New Zealand savings. Start with your income after tax in both countries. Count only the income which will keep coming once you have moved. Subtract what it costs to live at the destination, including rent, and location-specific costs such as health insurance and trips home. Subtract the yearly cost of visas and professional advice. Spread the one-off cost of moving over the years you expect to stay. What is left is the surplus. It builds wealth only when it is used to repay debt, saved or invested. If checked destination costs sat $3,000 a month below your current spending, that is $36,000 a year before those deductions.
Test the plan against the events which could overturn it. Those include a major health problem, a natural disaster in a country with limited emergency services, the loss of the remote income, or a visa rule changing at short notice. Long-term visas are country-specific, often carry income, insurance or investment thresholds, and change, so you will need to thoroughly check the current rules before committing. Eligibility for publicly funded healthcare and ACC cover apply in New Zealand. Australia and the United Kingdom give eligible visitors limited reciprocal healthcare, which covers some treatment and far from everything. For any destination, confirm local eligibility for healthcare, accident cover and the insurance you will need, and expect premiums to rise with age. Check which of your existing policies continue overseas. Some income protection and life policies cover you in Australia and elsewhere. Savings held in New Zealand dollars and spent in Fiji or the Philippines carry an open currency position, and exchange-rate movements will widen or shrink the advantage from year to year. Budget on a weaker New Zealand dollar than today's, so a fall is already catered for.
A remote arrangement resting on a manager's goodwill is a weaker asset than one written into your employment agreement. Employers can call staff back to the office, and some adjust pay to the employee's location or reserve the right to. Get the arrangement's permanence and its pay basis in writing before anything is signed. Price the move on the pessimistic case: the income you could earn at the destination if the remote job ended.
Moving to Australia is the most familiar version and it works in a different way to conventional geoarbitrage. Increased pay, instead of reduced living costs, usually drives the result, so the useful comparison is whether household income after tax rises once housing, superannuation, healthcare, relocation and return travel are counted. For some households moving to Australia pairs higher pay with lower housing costs outside Sydney and Melbourne; for others the higher pay is absorbed by the move or an upgraded lifestyle.
What Inland Revenue does when you leave
New Zealand tax residents pay tax here on their worldwide income, and non-residents pay tax here only on income sourced in New Zealand. Which you are decides what an offshore income costs you. Inland Revenue's tests run on days and on a home:
- You become a tax resident if you spend more than 183 days in New Zealand in any 12-month period, or if you have a permanent place of abode here
- You stop being one when you have been away for more than 325 days in any 12-month period and have no permanent place of abode in New Zealand
A permanent place of abode is a place where you usually live in New Zealand. You need not own it, and it need not be empty while you are away. Keeping a former family home and renting it out may contribute to IRD determining you kept a permanent place of abode, particularly where you lived there and keep enduring ties. The outcome depends on the full facts of your situation. Where both countries claim the right to tax the same income, a double tax agreement may decide which country treats you as resident, limit what each can tax, or give relief for tax paid twice. The result depends on the agreement and the income. International tax matters can be notoriously complex, so anyone planning to live abroad on New Zealand or offshore income should settle their residency position before leaving, with advice for both countries. The initial and any ongoing accountancy or tax filing fees are just a cost of the move.
NZ Super and KiwiSaver from overseas
NZ Super can continue in many countries, and it requires an application before you go. Eligibility criteria apply, and the amount depends on the destination. There are social security agreements with some countries, a separate arrangement with Pacific nations, and a general rate elsewhere based on years lived here. The United Kingdom is treated differently: a person living there cannot receive NZ Super and may qualify for a UK payment instead. Confirm the rule for your destination with Work and Income before you build a budget on it.
KiwiSaver savings are treated differently depending on the destination. Someone moving permanently to Australia may transfer their savings to a participating Australian superannuation scheme or leave them in KiwiSaver, and cannot withdraw them as cash on the strength of the move. Someone moving permanently anywhere else can withdraw most of their savings after a year overseas, and government contributions cannot be withdrawn.
Earning overseas income while living here
The same idea runs in reverse, and it works because cities such as London and New York are costlier for most people to live in than anywhere in New Zealand. A New Zealander employed remotely or as a contractor by a London or New York firm, on that city's pay, earns at the expensive city's rate and pays costs here. Income for work done here is taxable here once you are resident, and exchange-rate movements can widen or erase the advantage. Eligible new arrivals and New Zealanders returning after ten or more years away may receive a temporary tax exemption of about four years on most overseas income other than pay for work. Criteria apply, and it can end early: applying for Working for Families ends the exemption and the choice cannot be reversed.
Selling in the city and buying regionally
Most of us know someone who has moved within New Zealand with money as a main reason, and several of Become Wealth's Christchurch-based team made exactly that move from Auckland. The trade is lifestyle for liquidity: your net worth is the same on settlement day, but more of it is in cash you can use. With clients we have noticed day-to-day spending usually falls as well, mostly because there is less to spend it on. Fewer restaurants, concerts and sports events, and parking which is often free, add up over a year. Instead, people might spend more time hiking or walking. This sort of move suits people who want the regional life anyway, perhaps for more accessible outdoor pursuits such as hiking, fishing, skiing or camping. Lower prices in the regions often come with fewer specialised jobs, fewer services and thinner transport links, so the regional life has to work on its own terms.
The domestic version exists because house prices vary far more between regions than pay does. Across the year to May 2026 the median residential sale price was about $945,000 in Auckland, roughly $530,000 in Manawatū-Whanganui and under $500,000 in Southland. For the year ended June 2026, median weekly adult income from wages, self-employment and government transfers in those regions sat within a few percent of each other. It was about $1,000 in Auckland, $968 in Manawatū-Whanganui and $959 in Southland. Incomes differ little across those regions while house prices differ by 40 percent or more. These are population medians, and they do not show what the same person would earn after moving; that depends on their occupation and on whether their existing income can travel.
Selling the family home to buy a smaller one nearby releases less than most people expect, because smaller, newer, well-located homes are scarce here and sell at a premium. The Retirement Commission has highlighted the shortage of suitable homes to downsize into. Over the decade to 2023, one-person households grew by almost 120,000 while one-bedroom supply grew by about 40,000. Moving to a cheaper region avoids the shortage. You sell location, and buy the same floor area where location costs less. It is one of the few ways to turn a family home into accessible capital without borrowing against it.
For anyone still working, timing matters as much as the sum. Suppose a $1.5 million Auckland home is sold and an $850,000 regional home bought, and commission, legal fees, the move and initial repairs take about $100,000 of the $650,000 difference. Roughly $550,000 remains, and it is invested for the ten years before you draw on it. At an illustrative 5 percent a year after fees and tax but before inflation, it grows to about $896,000. Saving $1,500 a month from salary for the same ten years at the same return builds about $233,000. The move places almost four times as much into the portfolio after ten years, because it converts housing equity into investable capital at the start. Both are future nominal amounts, so their purchasing power will be lower than the figures suggest. Of course, this is an illustration; returns, fees, inflation and tax all need to be considered.
"Financial considerations are usually the easy part. The people who are glad they moved two years later chose the place for a package of reasons, often family, lifestyle or hobbies, climate and cost. I have never met anyone who made a lasting move based on price alone," says Jonny McNamee, private wealth manager at Become Wealth.
The capital freed up by selling in the city is what this version creates, and most of it can be spent without anyone deciding to. The regional house creeps up in specification, then comes the renovation, and the boat. Decide before settlement how the freed-up cash will be used, whether repaying debt, topping up an emergency fund or investing the sale proceeds. Then act on it promptly. If you sell one property to buy another, deduct every one of these from the difference between the two prices before you count the net sum:
- Agent commission and marketing
- Legal fees at both ends
- Moving and storage
- Bridging costs where settlement dates fail to line up
- The repairs and upgrades the new house needs
- Rates and insurance, which do not reliably fall with the house price
- Travel back to family and friends
If the sum left would barely change your mortgage or your retirement position, stay or wait.
Before you commit
For an unfamiliar destination, or a move which would be hard to reverse, live there first for long enough to include an ordinary working period and the least flattering season. Overseas this usually means a long-term Airbnb, a serviced apartment or a local lease, and in some countries it stays that way. Indonesia, for example, allows foreigners leases and use rights but never freehold title. Within New Zealand it may mean letting out your existing home for a period, or selling first and renting while the proceeds sit in deposits. Buying the next house before selling the current one adds bridging costs and the chance of carrying two properties, so price that sequence before choosing it. Each option has a cost, and each cost can be known before you commit, which a failed move cannot.
Reversibility has more than one form. Financially, a house sold in an expensive city can be hard to buy back if prices there outpace the destination's. In employment, the former job may be gone, and a remote arrangement can change with a new manager. In a relationship, one partner may experience the move differently once seeing family means a flight. Treat the move as probably permanent, and agree which partner is keen and which is going along with it before anything is signed.
The place and the numbers both need to work
In our experience the moves which last rest on a package of reasons: family, work, climate, community, access to the outdoors and cost. The financial advantage matters, and it cannot carry a place the household would not otherwise choose. If the destination appeals only because it is cheaper, the released cash tends to go on making it bearable. Choose a place the household would keep if the numbers turned out ordinary, and let the numbers decide how much better off you are.
This article is general information which is not intended to provide financial advice of any kind. It does not take your circumstances into account. Nothing in this article constitutes a recommendation to buy, sell, or hold a financial product or other asset. For more information refer to our website terms and conditions, and financial advice provider disclosure.
Make better financial decisions
Fortnightly insights on investing, personal finances, retirement, KiwiSaver, tax, and property, so you can build and keep real wealth.